
The EU Emissions Trading System (EU ETS) has long been one of the most important instruments of European Union climate policy. This article gives a clear summary of the essentials of the EU ETS and the related carbon footprint calculation for everyone to whom these rules apply. You will learn how the system works, which steps to follow when monitoring your carbon footprint accordingly, and how it compares with the GHG Protocol standard.
It will hardly come as news that, through an ambitious climate policy, the EU is working towards “climate neutrality” by 2050. One of the key instruments of this plan is the emissions trading system known as the EU Emissions Trading System (EU ETS). The system, which covers not only EU Member States but also Iceland, Liechtenstein and Norway, was launched in 2005 to reduce greenhouse gas emissions cost-effectively. By setting emission caps and allowing allowances to be traded, the EU ETS is designed to encourage energy-efficient solutions and technological innovation. At the same time, it aims to steer the European economy towards a lower-carbon model.
Under the EU ETS, companies monitor direct emissions from their operations (Scope 1 under the GHG Protocol). This not only fulfils their legal obligations but also gives them an overview of where processes can be optimised. Calculating and reporting a carbon footprint helps companies understand how their activities affect climate change and identify opportunities to reduce that impact. The EU ETS currently covers the most emission-intensive industrial sectors, including energy, steel, cement, chemicals and paper, as well as aviation within the European Economic Area. Together, these sectors account for roughly 36% of greenhouse gas emissions in the EU.
Whether a company falls under the EU ETS can be determined from Annex I of the EU ETS Directive, which lists the regulated sectors and activities. In the Czech Republic, detailed information and support are also available from the Ministry of the Environment and the Czech Environmental Inspectorate.
In the coming years, EU ETS 2 will be introduced, extending the existing system to further sectors. It will newly cover fuel combustion in buildings, road transport and related industrial sectors. The aim of this change is to make emissions from heating homes and commercial buildings and from road transport subject to carbon pricing as well. Fuel suppliers will start monitoring emissions as early as 2025, and from 2027 emissions from the EU ETS 2 sectors will be priced by bringing emission allowances to the market.
“Cap and trade”: the principle behind the EU ETS
The EU ETS works on the “cap and trade” principle. The EU sets an annual emissions cap that limits the total quantity of greenhouse gases the covered sectors may emit. Entities covered by the EU ETS must demonstrate that they hold enough emission allowances; if they do not, they face a fine and must buy the missing allowances. The cap is lowered every year so that emissions within the EU fall over the long term. Companies receive emission allowances free of charge or buy them (trade), and each allowance entitles the holder to emit one tonne of CO₂ equivalent (CO₂e).
A company that emits less can sell its unused allowances, while companies that exceed their limit must buy more. Companies that can cut their emissions at a cost below the allowance price therefore decide whether it pays more to reduce emissions through operational innovation or to buy emission allowances. This market mechanism supports investment in clean technologies, ensures that emission targets are met and, as the cap keeps falling, increasingly motivates companies to reduce their emissions.
How to calculate your carbon footprint under the EU ETS
The basic steps in measuring a carbon footprint under the EU ETS are as follows:
- Preparing a monitoring plan
First, you need to prepare a monitoring plan (MP), which every installation must submit for approval to the competent authority, in the Czech Republic the Ministry of the Environment. Above all, the plan identifies all emission sources, defines the methods used (calculation or measurement) and sets the level of accuracy under the tier system. After registration in the Union Registry and, where relevant, a voluntary application for free allocation of allowances, monitoring of direct emissions of carbon dioxide (CO₂), nitrous oxide (N₂O) and perfluorocarbons (PFCs) begins using the methods above, for the given calendar year. - Data collection, calculations and obtaining allowances
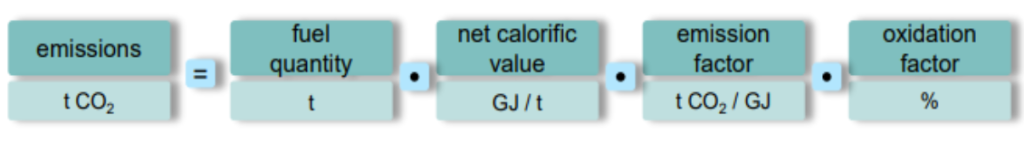
Fuel consumption data, emission factors and oxidation factors are used to calculate emissions according to harmonised rules. The next step is to obtain emission allowances in one of three ways: at auction, by buying them on the market from other EU ETS participants, or through free allocation. Free allowances are allocated every year on 28 February, while allowances from auctions and the market are available on an ongoing basis depending on supply and demand. - Reporting and verification
Companies submit annual emissions reports, which are checked by independent accredited verifiers. Once verified, the report is sent together with the verification report to the competent authority no later than 31 March of the following year. By 30 April, operators then surrender the number of allowances needed to cover their verified emissions for the previous calendar (monitoring) year.
The tier system in the EU ETS
The calculation method uses data on fuel consumption, its net calorific value, emission factors and oxidation factors to calculate total emissions. The measurement method, by contrast, relies on direct measurement of emissions with certified equipment that provides accurate real-time data. The EU ETS tier system sets the required level of accuracy and data quality for emissions monitoring: a higher tier means greater accuracy and more demanding measurement methods. This ensures that larger installations with higher emissions use advanced methods, while smaller installations can apply simpler procedures.
Under the GHG Protocol, the carbon footprint always comes out higher than under the EU ETS
The GHG Protocol has already come up on the CSRD website. It makes sense to compare the EU ETS approach to carbon footprint monitoring with this widely used standard.
The EU ETS focuses only on direct emissions from processes controlled by the installation, such as the combustion of fossil fuels or emissions from chemical reactions, which broadly corresponds to Scope 1 under the GHG Protocol. The GHG Protocol, however, covers a wider range of emissions. It includes Scope 1, Scope 2 (indirect emissions from purchased electricity, heat and steam) and Scope 3 (other indirect emissions across the supply chain). “In practice, companies that buy emission allowances under the EU ETS are wary of reporting their carbon footprint, because under the GHG Protocol it will always come out higher, so there is a real risk of being accused of greenwashing. These companies therefore need to pay closer attention to how they communicate the results of their carbon footprint calculation,” warns Lukáš Ferkl, CTO of EnviTrail.
So what are the main differences between the EU ETS and the GHG Protocol?
- Methodology: The EU ETS requires fixed formulas and emission factors defined by regulation, which ensures consistent and comparable data across participating installations. The GHG Protocol, on the other hand, allows more methodological flexibility, including the use of primary or secondary data and different emission factors depending on the region or data availability. Comparing the results of different companies under the GHG Protocol is therefore very problematic.
- Scope: The EU ETS requires companies to report only regulated emissions within defined sectors (e.g. energy, industry, aviation), whereas the GHG Protocol supports a comprehensive approach to measuring emissions. These differences reflect the different aims of the two systems: the EU ETS focuses on regulating emissions in the EU’s emission-intensive sectors, while the GHG Protocol is a tool for comprehensive carbon footprint management for practically every type of company.
Linking with CBAM is intended to support decarbonisation beyond the EU’s borders
In future, the EU ETS is to be complemented by the Carbon Border Adjustment Mechanism (CBAM), which is currently in the first phase of its transitional period. CBAM is designed to ensure that products imported into the EU face a carbon price similar to the one paid by European companies covered by the EU ETS. Importers of products from third countries will be required to surrender certificates corresponding to the carbon emissions associated with producing the imported goods. The mechanism aims to level out differences between countries with strict climate policies and those without such regulation, protecting the competitiveness of European manufacturers while supporting global decarbonisation efforts.
Summary: the EU ETS and the GHG Protocol as reference points for European companies on the way to sustainability
The EU ETS focuses on companies’ direct emissions (essentially Scope 1 under the GHG Protocol) and regulates specific sectors. Assessing greenhouse gas emissions across the full scope of the GHG Protocol (Scope 1–3), by contrast, gives a more complete picture of the reporting company’s impact on climate change. The reporting obligation under the CSRD, which allows companies to report their annual emissions results in line with the GHG Protocol, applies to a wider range of companies than the EU ETS. What both systems have in common, however, is that they support the EU’s ambition to achieve climate neutrality by 2050 and motivate companies to innovate and become more efficient. The introduction of CBAM (the Carbon Border Adjustment Mechanism) also extends the reach of this regulation beyond the EU’s borders, strengthening global responsibility for decarbonisation. Combining the EU ETS and the GHG Protocol thus not only strengthens corporate transparency and accountability but also steers European businesses and the economy towards a more sustainable future.
Authors
Petr Tomáš and Anna Zora Kloužková
EnviTrail